Blog· October 7, 2026
How to read a preliminary notice before you extend open account terms
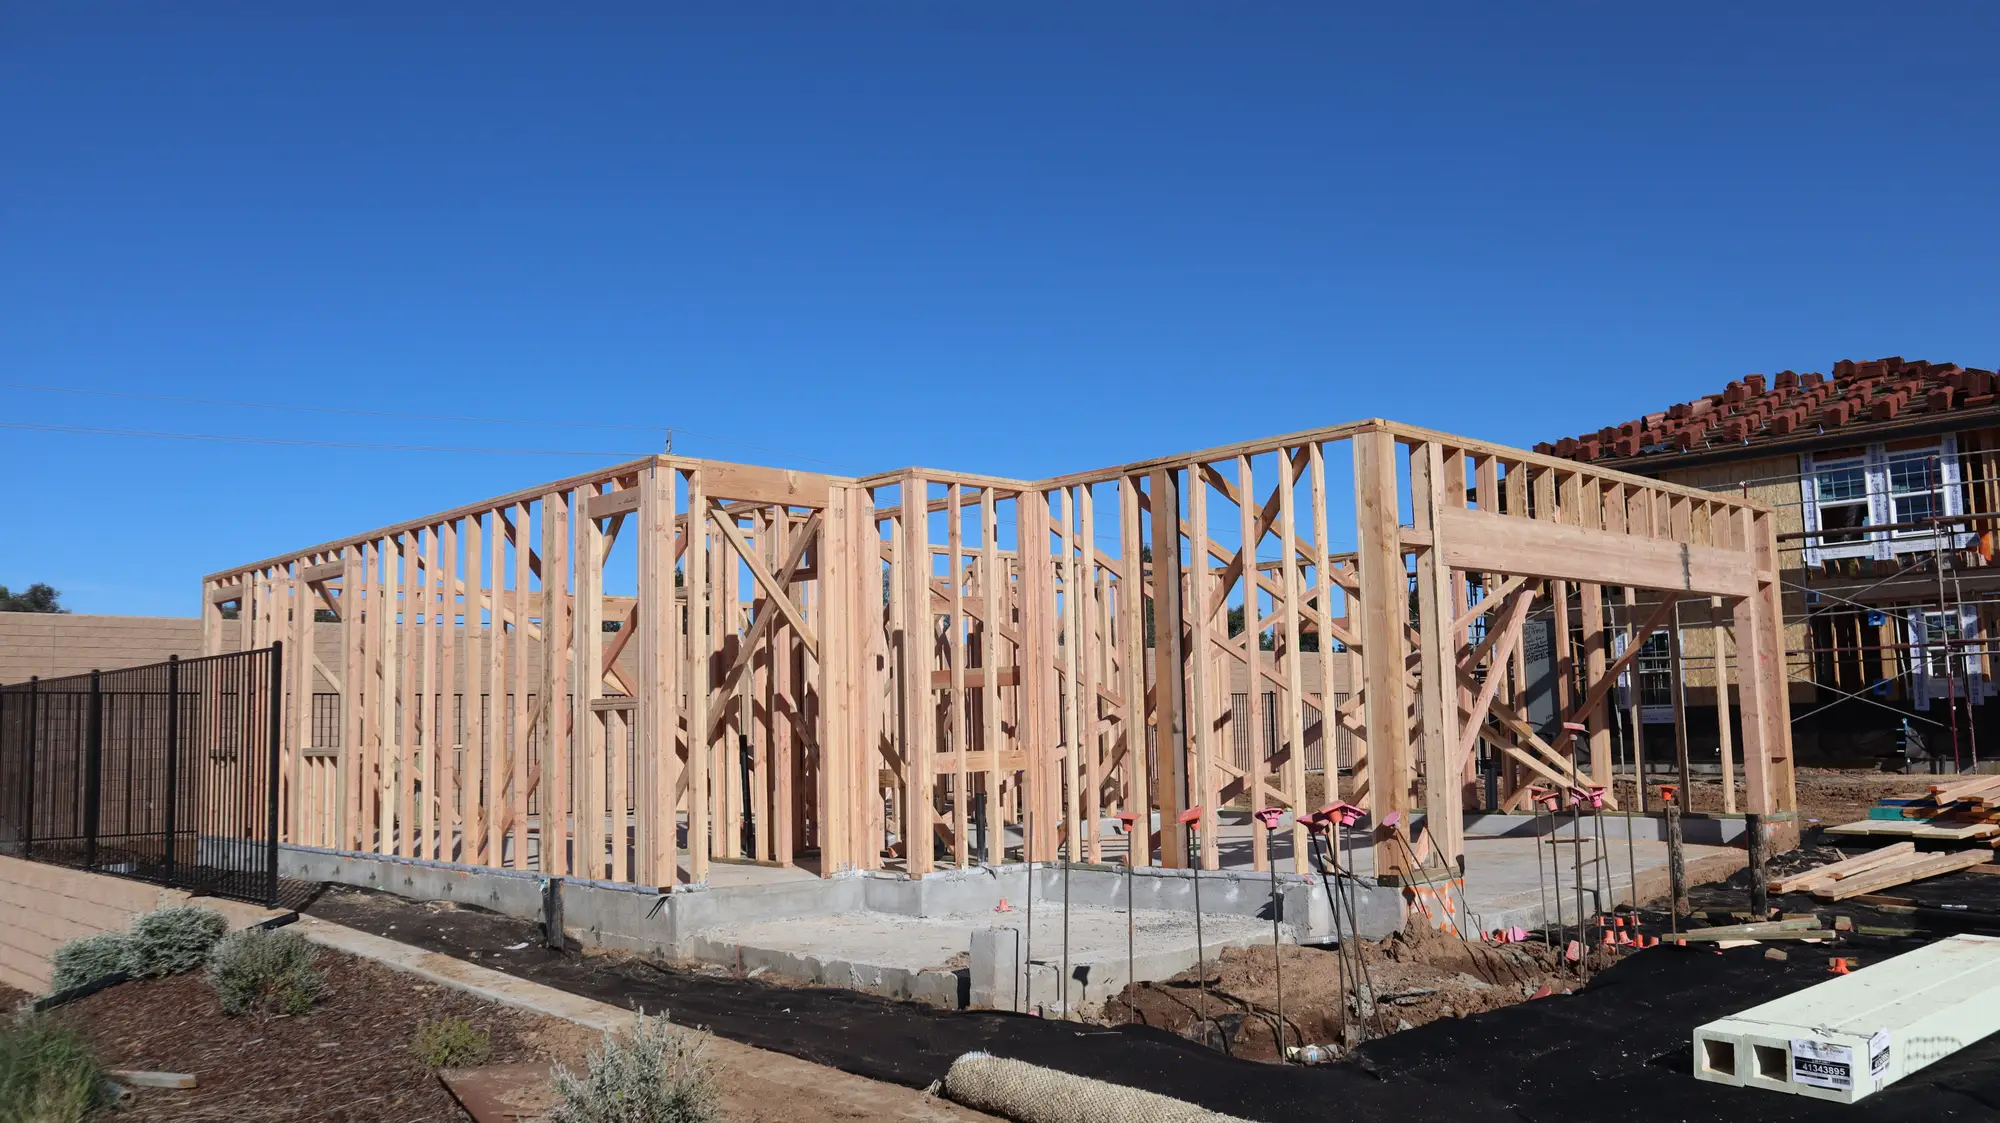
A preliminary notice shows up in the mail or through a notice-filing service, and the instinct is to treat it like a green light. A contractor or supplier downstream filed it, which means there's a real job with a real general contractor and a real owner. That's useful. It's also where most people stop reading, and it's the wrong place to stop if you're about to set a credit limit.
What the notice establishes
A preliminary notice (sometimes called a pre-lien notice, notice to owner, or 20-day notice depending on your state) is a procedural step. The filer is preserving lien rights in case they don't get paid. It tells you:
- The project exists on paper, with a permit number or legal description tied to it
- A specific GC or owner is named, so you can match it against your own AR
- Someone in the chain expects to supply labor or material soon
That's a real signal. A project with no preliminary notices filed at all, eighteen months after permit issue, is usually a project that never broke ground or got shelved. So the notice is worth pulling. It doesn't prove the site is active today.
What it doesn't tell you
State deadlines push filers to send the notice early, often 20 days from first furnishing, so a notice dated six weeks ago doesn't mean six weeks of continuous work. It means someone started the paperwork six weeks ago.
It also doesn't tell you what happened after. A job can get a foundation poured, stall for financing reasons, sit for four months, and the preliminary notices on file never change. Nobody files a retraction when a project goes quiet. The notice captures intent at the moment it's filed. It doesn't track what the job does afterward.
This matters most on the accounts where you're deciding whether to open terms or extend a limit based on "there's a permitted, noticed project behind this." A GC with three preliminary notices on file for a mixed-use build can still be sitting on a graded lot with no framing started. The notice and the job site are two different records, and only one of them tells you if concrete is being poured this month.
Cross-checking before you set terms
Pull the permit, confirm the notice names match your application, and check separately whether the job is moving. That third step is where most credit files are thin: a drive-by confirms one address at a time and doesn't scale past a handful of accounts, and a draw inspection report often lags what's happening on site by weeks.
For accounts above a certain exposure threshold, it's worth having a dated answer to "is this site active, stalled, or showing no ground activity" that updates on its own schedule instead of only when someone happens to drive past. Pipeline Validation does exactly that: it runs your permitted-project list against a monthly pass and hands back a dated verdict per project, so a preliminary notice that's six months old and a job site that's been quiet for four of those months don't get treated the same way on your next credit review.
None of this replaces your underwriting judgment on the notice itself, the contractor's pay history, or the owner's financing. It closes the gap between what got filed and what's being built, which is usually the gap that turns a clean-looking account into a slow-pay surprise.
If you're setting or renewing terms against a list of permitted jobs, it's worth seeing which of them are under construction before the limit goes out.